
China's Q3 Smartphone Split: Volume Down, Prices Up, Foldables Still Sliding
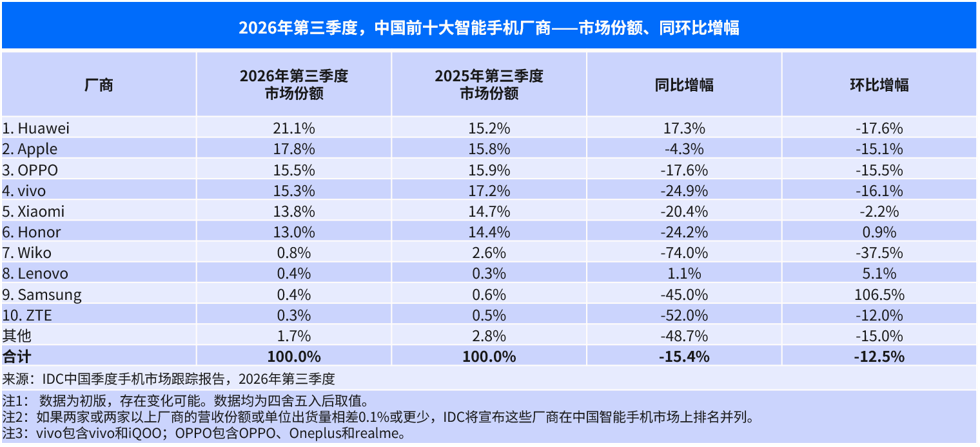
China's handset business no longer moves as one market. The third quarter produced a textbook volume down, price up pattern: vendors competed for share at the top of the price ladder while the entry band collapsed, and the category carrying most of the design excitement kept shrinking. The share standings, the price-band shifts and the foldable tally below explain how each vendor reached this position and what still has to happen before demand stabilises.
Share standings after the third quarter
| Vendor | Q3 share | Standing | What moved it |
|---|---|---|---|
| Huawei | 21.1% | Leader | Shipments grew at a double-digit rate year on year |
| Apple | 17.8% | Second | New models drew a response better than expected, but a leaner line-up left shipments slightly lower |
| OPPO | 15.5% | Top three, held for four consecutive quarters | Triple-digit year-on-year shipment growth in the $600-and-above tier for three consecutive quarters |
| vivo | 15.3% | Fourth | First place among Android brands above $600 |
| Xiaomi | 13.8% | Fifth | Returned to third in foldables; first place in Android above $1,000 and in the sub-$100 band |
| Honor | 13.0% | Head-tier vendor | The only brand among the leading vendors to record positive quarter-on-quarter shipment growth |
Two product-level readings sit behind those numbers. Apple's constraint was line-up breadth rather than reception, while Honor's Magic9 series was the only mainstream flagship launched this year whose opening sales rose meaningfully against the previous generation.
Price structure: the ladder is being re-cut
Instead of absorbing low-cost inventory, the market is trading up, and cost pressure is accelerating that migration toward the mid and high tiers. Year on year, share in the $600-and-above premium band expanded by 7.1 percentage points; the $400-$600 upper-mid band widened by 4.6 percentage points; the sub-$200 band gave back 13.9 percentage points.
Foldables: a fourth consecutive quarter of decline
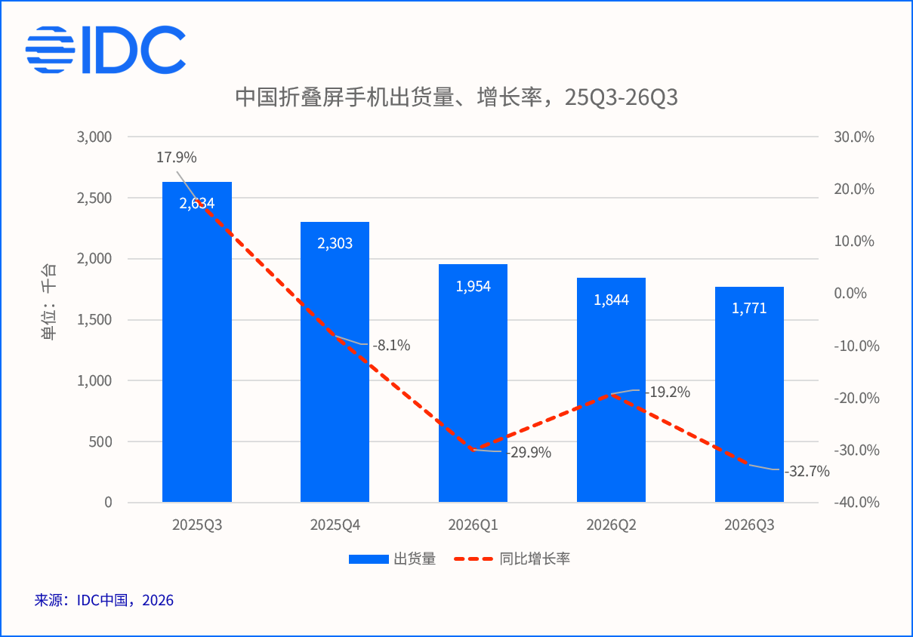
China's foldable shipments reached 1.77 million units in Q3, 32.7% below the same quarter last year and the fourth straight quarter of annual contraction. Huawei's lead is absolute, holding over 70% of the category; Samsung follows in second at 8.0%; Xiaomi has returned to third at 6.4%. With Apple stepping into the segment and more brands set to unveil wide-fold products in the first half of 2027, the market is expected to stop falling and begin recovering from the next quarter.
What has to happen before demand turns
IDC's working assumption is that memory and other component costs stay elevated through the coming quarters. On that basis, the China smartphone market sees little relief in Q4 2026 and the downtrend runs through most of 2027. Space for the other brands opens only once consumers grow accustomed to the new price system and the next replacement moment arrives.
The sequencing is the story of this cycle: the premium and upper-mid bands are already taking share, the entry band is thinning out, and the foldable restart is tied to product timing rather than to a demand recovery that has already begun.