
Anthropic IPO Reset Explained: Why Wall Street Now Talks $1.5–1.6 Trillion, Far Short of $2 Trillion
By James Hartley | IT Insights
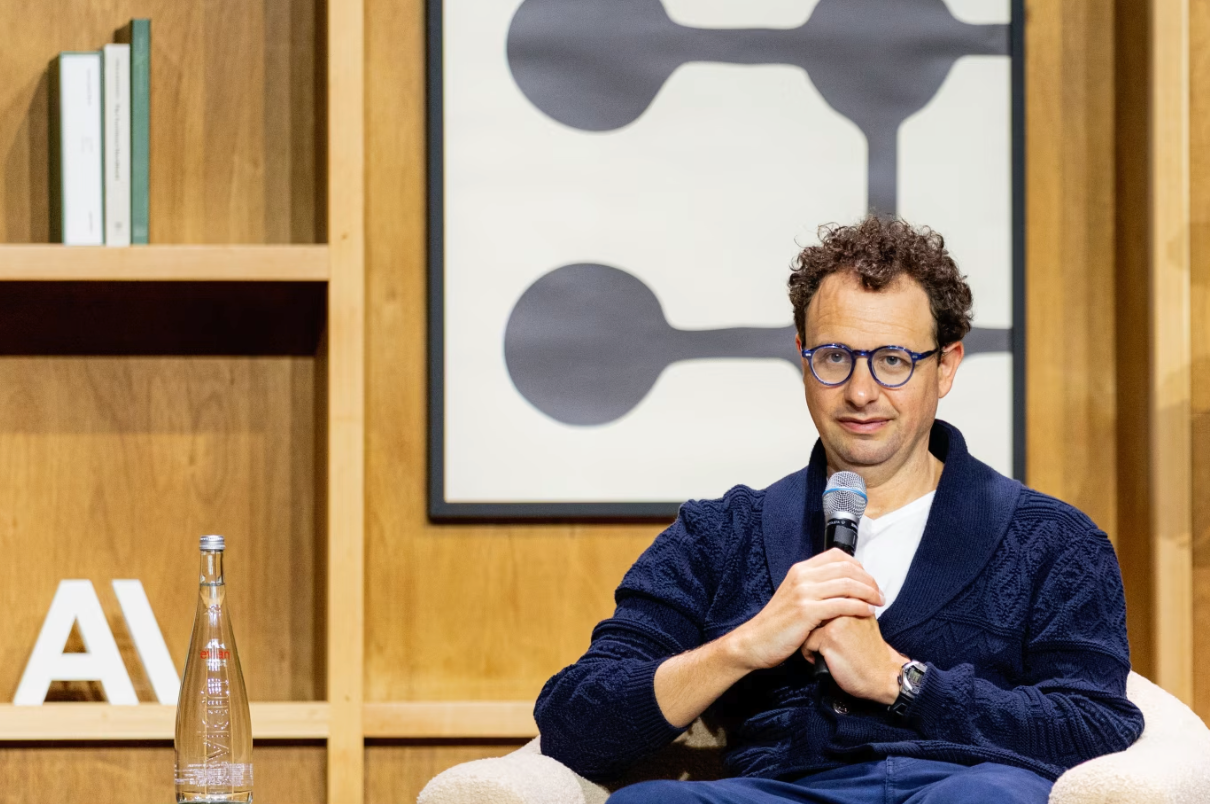
Image: Anthropic CEO Dario Amodei.
A headline valuation and a final offer price are not the same object — and holding that distinction in mind explains most of the noise around Anthropic's planned listing. The expectation being circulated now is a price tag of $1.5 trillion to $1.6 trillion, far short of $2 trillion and visibly below the close to $2 trillion figure that had been trading as folklore in recent months. What actually changed is not the quality of the company's models or the demand for its services; it is the burden of proof. After a week in which megacap earnings reset the market's patience, institutional buyers are no longer asking how fast AI revenue grows, but how much of that growth survives depreciation, energy constraints and political friction. That is the honest frame for the reset — and it is also the frame most summaries skip.
Three conclusions before the detail
- The reset is a tape problem, not a product problem. The revised bracket was communicated by investors over the past few days, immediately after public-market turbulence lowered what comparable stocks would tolerate.
- A cautious print can still produce the headline number. Several investors argue that even pricing at about $1.5 trillion may leave the company valued at $2 trillion by the end of the first trading day.
- The last real lever is supply. Anthropic has not fixed its valuation target and is still weighing how much stock to place — the variable that converts a headline number into an actual clearing price.
What the investors actually put on the table
People familiar with the discussions say institutional investors told Anthropic and its advisory team in the past few days that the listing scheduled for later this month should sit at $1.5 trillion to $1.6 trillion — well under $2 trillion, and clearly below the close to $2 trillion level that had circulated in recent months. The concerns they listed: unsettled equity markets, a growing unease about how much AI exposure a single portfolio can absorb, political pushback against data centres, and the unresolved question of when hyperscale cloud operators such as Amazon and Meta will translate AI spending into visible profit.
The sequence matters. Anthropic has not finalised a valuation target and is still working out how much stock to sell. Some investors had already been telling the company that its number should sit closer to $1.5 trillion after last month's investor day — but that was before last week, when technology shares suffered a double-digit decline as Intel and Alphabet fell on a string of disappointing results. In other words, the discount existed before the sell-off; the sell-off merely made it defensible in public.
Why the ceiling moved down: four pressure points, ranked
- Market volatility and concentration risk. A debut of this scale cannot be priced against a falling tape, because index funds and mutual funds must buy it at whatever number is set — and their clients are the ones who absorb the regret if the number is wrong.
- The hyperscaler profit question. The same companies that finance AI infrastructure are the ones whose reported margins investors watch for confirmation that the build-out pays. Goldman Sachs Research's published baseline model implies roughly $765 billion of annual AI capital expenditure in 2026, rising toward $1.6 trillion a year by 2031 — an extraordinary build that only makes sense if revenue and margin follow. Until Amazon and Meta show that follow-through, every AI listing is priced at a discount.
- Physical and political constraints. Training and serving frontier models requires data centres, and data centres now require municipal consent. The Brookings Institution reported in mid-2026 that at least 15 states had considered pauses on data-centre development and at least 100 localities had already adopted their own restrictions; New York became the first state-level moratorium on large new facilities, according to the advocacy group PIRG. This is a schedule risk that converts directly into cost risk.
- Private-market repricing came first. Reuters reported on 26 October that some existing and prospective investors were already marking the company at about $1.5 trillion, down from roughly $2 trillion a week earlier, having reviewed the company's financial disclosures. Public-market volatility did not start the reset; it ratified it.
Two price tags, one company
| Dimension | The $1.5–1.6 trillion bracket | The close to $2 trillion expectation |
|---|---|---|
| Where it came from | Investor feedback over the past few days; some voices as early as last month's investor day | Circulated in recent months, including talk of a record-breaking listing |
| Market it assumes | Volatile tape, double-digit declines in megacaps, cautious fund flows | Continued AI momentum and appetite for growth stories |
| What must be true | Growth endures, but margin proof can lag one or two more years | AI spending converts to profit visibly, starting with Amazon and Meta |
| Who wins | First-day buyers; the underwriting syndicate avoids a broken debut | Existing shareholders and late private-round entrants |
| Who loses | Existing shareholders, who accept a smaller paper mark | The public portfolio manager left holding the stock at the open |
| Risk if wrong | Leaves money on the table if demand outstrips supply | Creates a reference price the whole AI complex must defend |
The conservative-print logic: set a low bar, collect the pop
Several investors say they expect Krishna Rao, Anthropic's chief financial officer, to set a deliberately cautious valuation and to prioritise giving IPO buyers a burst of upside on the first day of trading. In their arithmetic, even a listing at about $1.5 trillion could send the shares high enough to lift the company's market value to $2 trillion by the end of the first trading day. The precedent they point to is closer than most commentators note: SpaceX, the rocket company controlled by Elon Musk, surged 30% on its first day of listing in June — yet that occurred before investors' general anxiety about AI had formed, so the same pop should not be assumed as a baseline.
Read as an incentive story, the logic is coherent. Underwriters earn their standing by placing enormous deals that do not collapse, and a deliberately modest range transfers upside to the buyers who will hold the stock in index portfolios for years. For general readers the lesson is procedural: the number that appears in the final prospectus is a negotiation outcome, not an estimate of intrinsic value.
Precedent check: what history says about records
| Listing | Key fact | What it teaches about Anthropic |
|---|---|---|
| Alibaba, September 2014 | Raised about $21.8 billion on the NYSE — the largest U.S. listing at the time (Reuters, Investopedia) | A record deal can price conservatively and still become a market event |
| Saudi Aramco, December 2019 | Debut was built on a very small percentage of shares outstanding | Floating a fraction of the company is how issuers protect price at enormous scale |
| SpaceX, June listing | Up 30% on the first day of trading (per the original report) | First-day pops are possible, but were set in a pre-anxiety tape |
| Anthropic, planned this month | Valuation target not final; share size still undecided | The supply decision is the last unpriced variable |
Timeline and mechanics: what to watch next
Anthropic intends to begin its roadshow to investors as early as next week, with the listing itself expected in the week before Thanksgiving. The number and the price band arrive together: when the roadshow begins, the company will disclose how many shares it hopes to sell and the target price range, and those two figures set the target valuation in public.
Checklist of the signals that matter between now and the listing:
- Offer size — how many shares go out, because a smaller float cushions the first-day pop; a larger one exposes it.
- Price-band width — a narrow band implies confidence; a wide one implies the book is still being built.
- Which accounts anchor the deal — index-heavy and long-only buyers stabilise the first week; short-horizon funds do not.
- The tape around the roadshow — megacap earnings and hyperscaler capex guidance now move the price band as much as any company-specific disclosure.
- Data-centre and energy headlines — new moratoriums or grid-cost disputes are schedule risk becoming pricing risk.
One procedural note often lost in coverage: under U.S. law the marketing tour cannot open until a registration statement is on file, a point the Congressional Research Service spells out in its primer on public offerings. Anything described as "the valuation" before the band is published is a negotiating position, not a price.
Five common misconceptions
- "A lower valuation means the business deteriorated." The reported reset followed public-market declines and portfolio risk limits, not a change in demand for the company's models.
- "A first-day pop means the IPO was mispriced." In deals of this size, leaving money on the table is a feature of the underwriting relationship, not a mistake.
- "$2 trillion is now off the table." It is off the table as an offer price, while several investors describe it as a plausible market value by the end of the first trading day.
- "Retail investors can simply buy at the offer." Allocation in a deal this oversubscribed flows first to institutional accounts; the entry point for most households is the aftermarket.
- "AI listings are all one trade." Compute suppliers, cloud operators and model developers have different margin clocks; the repricing hit each of them at different speeds.
A judgment framework you can reuse
When the next mega-IPO headline lands, run it through six questions before forming an opinion:
- Is the number an offer price, a market value or a private-round mark? Only the first is contractual.
- What changed in the public tape in the days before the report? Attribution beats intuition.
- Does the company's cost base depend on assets that depreciate faster than they earn? Ask for the useful-life assumption.
- Who bears the physical constraints — power, land, permits — and are they already priced?
- What does the float size tell you about how much protection the issuer expects to need?
- Is there a cash-flow bridge from today's losses to a plausible margin, or only a growth curve?
FAQ
How much will Anthropic's IPO actually be worth?
No target is final. Investors have pushed toward $1.5 trillion to $1.6 trillion; the decisive disclosure arrives when the roadshow begins and the share count and price band are published.
Why is a listing at about $1.5 trillion still a $2 trillion story?
Because offer price and traded value are different moments. Several investors expect a first-day rally, though the June comparison — SpaceX's 30% surge — happened before AI scepticism took hold.
When will it list?
The offering is expected later this month, in the week before Thanksgiving, with the investor roadshow starting as early as next week.
Should ordinary readers care about the number?
Yes, but not as stock advice. A listing of this scale enters index funds, resets how banks price AI credit and sets the tolerance for every subsequent tech offering — effects that reach households through pensions and mutual funds.
What would make the valuation move again?
Two things on the current calendar: evidence of AI profit at Amazon or Meta, and clarity on whether data-centre restrictions keep spreading state by state.
Sources and disclosure
Additional material in this piece draws on Reuters coverage of investor repricing (26 October 2026) and its database of the world's largest listings, Goldman Sachs Research's published AI capital-expenditure model, the Brookings Institution's analysis of data-centre moratoriums, and the Congressional Research Service primer on public offering rules. Company figures, timing and valuation ranges follow the original report; where sources disagree, the original report's facts prevail.
Written by James Hartley for ItInsightsWorld. Questions or corrections: contact@itinsights.com. This article is general information, not investment advice.